Friday, September 27, 2024

Instant Reaction: Mortgage Rates NAR

Jessica Lautz

Dr. Jessica Lautz is the Deputy Chief Economist and Vice President of Research at the National Association of REALTORS®.

Content by Jessica Lautz

Facts: The average 30-year fixed mortgage rate from Freddie Mac fell to 6.08% this week from 6.09% last week. At 6.08%, with 20% down, a monthly mortgage payment is $1,935 on a home with a price of $400,000. With 10% down, the typical payment would be $2,177.

Positive: This is the lowest weekly average since September 2022. Interest rates are down 1.71% from October 2023. The savings on a $400,000 home would be $366 monthly and $4,392 annually. The mortgage interest rate one could receive this week is well below the historical average (dating to 1971) of 7.72%.

Negative: Mortgage rates are not likely to come down in a meaningful way for home buyers. While there could be minor reductions in mortgage interest rates, those waiting for further improvements in affordability could be priced out further as home prices continue to climb.


Just blogging & sharing info I think you'll find valuable.
Reach out to us for any questions, thoughts. needs
KeepYourWitz@SBCGlobal.net
(661) 313-5470


Thursday, September 19, 2024

Laundry Rooms ~ Fancy Schmancy, or Work Horse?

So, I was perusing through Houzz looking at home stuff. Yeah, I like to do that. Our home in California has room for washer/dryer/sink and lots of cabinets. Our lake house home has that, plus a built-in ironing board and a long counter. With a linen closet and space for another folding table AND a chest freezer. Well, and TWO windows too.

As much as I'd love to 'decorate' both our laundry rooms, I just don't. If I'm selling a house, then heck yes, I'll even stage a laundry room!


I dig the sink in this and the open shelves, 
but you give up too much cabinet storage in this design.


The wallpaper on this one caught my eye. 
Wallpaper is making such a comeback!


My pups would totally sit in there 'helping' me do the laundry!


Dang, this is super fancy-schmancy!
Under cabinet lighting in a laundry room?


I LOVE this one. Absolutely love it. 
But, nope, wouldn't bother with cutsey-pie decor!


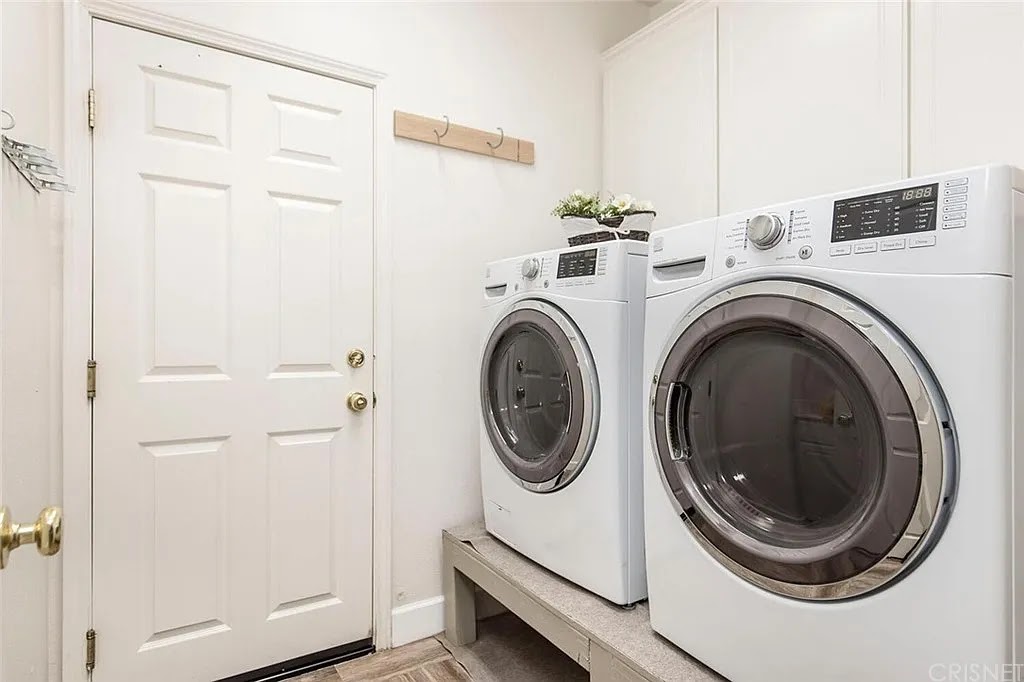
California house. 
Resting a basket of flowers heading out to stage someones house!


Lake House. 
Biggest laundry room I've had EVER!! 
But, see? No decor!

If you want even more ideas, enjoy the Houzz article below!


Friday, September 13, 2024

Market Minute Write-Up From C.A.R.

You'll be able to tell that these are not my words, very quickly. Well, if you have read my posts over the years you'll know.

From September 09, 2024 – The market has been relatively quiet in the lead-up to the Federal Reserve’s meeting on interest rates next week. Although recent economic data remains relatively strong, markets remain optimistic that the key policy rate will be cut by the Federal Open Market Committee. This has already begun to have a positive impact on the market as signs of homebuyer demand have perked up in recent weeks. However, prices continue to rise as well and that has helped to keep homebuyer sentiment restrained. The full benefit of lower rates will continue to play out in the coming months, but fortunately, the anticipated uptick in demand is also poised to be met with additional inventory, which is also slowly being unlocked as interest rates normalize.

Jobs data shows labor shortage shrinking: Two separate reports released last week show that the labor markets remain relatively healthy, but that the labor shortage that has driven much of the remaining inflation has eased. Headline job growth in the Commerce Department’s latest release came in at 142,000, which is slightly slower than during the first half of 2024, but remains in positive territory. At the same time, the report on job openings showed that there are fewer unfilled positions. In May of 2022, there were roughly 6.2 million more open positions than there was unemployed labor supply that was looking for a job. Last month, the shortage dipped to just 510,000 and was the first time the U.S. economy has been less than 1 million workers short since the economy reopened in earnest back in 2021. This should help inflation to keep trending toward the Fed’s 2% target as we approach the end of the year.

Interest rates continue their slide: As all eyes turn to the Federal Reserve’s Open Market Committee meeting next week, bond prices have risen in anticipation of a rate cut and mortgage rates have benefited from a strong treasury market in recent weeks. Last week, Freddie Mac’s average 30-year fixed-rate mortgage rate held steady at 6.35% and today’s daily quotes were down slightly more, averaging 6.27%. This represents a more than 100-basis point improvement in rates from a few months ago, though most of the benefit of the upcoming rate cut may already be priced into today’s mortgage rates. Notably, average rates for VA and FHA loans have already dipped below 6%, which should also help to generate additional housing inventory as the so-called lock-in effect diminishes somewhat.

Mortgage applications and pending sales: Although the level of mortgage applications and pending sales are still relatively low, compared with the decade-high levels reached back when rates were 3%, they are holding up much better to the seasonal slowdown than has been the case over the past two years. In fact, as rates came down in July and August, pending sales began to re-accelerate with preliminary analysis showing another double-digit gain in pending sales last month. In addition, September mortgage purchase applications are threatening to exceed the prior year figures for the first time since May 2021. Regionally, most parts of the state are within the margin of error, but the Central Valley slightly outperformed the Bay Area and the Far North in terms of housing demand last month, with Southern California and the Central Coast landing in the middle of the pack.

Construction activity continues to lose momentum: U.S. construction spending remain soft, with the total outlays dropping 0.3% in July. The decline was worse than consensus expectations, as economists had predicted a monthly decrease of 0.1%. Residential construction declined on a month-to-month basis for the first time in four months after revision on prior months’ data, with the latest drop attributed primarily to the weakness in single-family construction. In July, spending on new single-family dipped 1.9% from June, while new multifamily was essentially flat from the prior month. On a year-over-year basis though, new single-family remained sharply higher than a year ago by 7.7%. New multifamily dipped from 12 months ago by 6.7%. The pullback in overall construction spending was due again to elevated interest rates, despite the fact that rates started trending back down in early July. Lower interest rates should help revive builder sentiment in coming months, but housing permits from recent reports suggest that building activity will remain weak in the short term.

Homebuying sentiment stalls despite an increase in mortgage rate optimism: The Home Purchase Sentiment Index released by Fannie Mae inched up in August as consumers felt more positive about the mortgage rate environment. The share of consumers who believed that mortgage rates will go down over the next 12 months increased sharply by 10 percentage points from July’s 29% to August’s 39%. Meanwhile, those who expected home prices to decrease over the next 12 months increased moderately from 21% in July to 25% in August. Despite an improvement in the optimism in future direction of mortgage rates, the share who said that it is a good time to buy remained unchanged at 17% last month. With rates moderating to the lowest level since April 2023 and home prices expected to come down as the market transitions into the off season, homebuyers’ optimism will hopefully improve in coming months. Those who said that it is a good time to sell also remained flat at 65% in August. The stall in home selling confidence could be attributed partly to seasonal factors, but homebuyers staying on the sideline might also be a contributing factor. 

So, what do you think about all of this info? Do you agree? Disagree? Have any thoughts to share?


Friday, September 6, 2024

It's That Time Again!

I try to keep you informed of all things Real Estate related. Was actually going to blog about the NAR Settlement again. Talked with Leslie for an hour and a half yesterday and that was a large part of the conversation. Seems so unfair to Buyers. So many are scraping to buy a home, particularly now, and this just hits hard. 

At any rate, it's that time of the month to blog about home sales in boiling hot😔Santa Clarita Valley and it's surrounding neighborhoods. Acton to the East, Stevenson Ranch to the West, Castaic North, Newhall South.


As of right now we have:

15 in the Coming Soon grouping - exactly the same as last month.
571 Active - that's 20 more than last month.
In Escrow we have 301 - 30 less than last month.
Sold in the last 30 days? 266, actually 25 more than last month.

Interest rates have dropped down, thankfully, market time is definitely a bit longer. Insurance problems are hampering, but getting worked through. 

We are here to help in any way possible. We are happy just to chat, consult, discuss. Whatever your needs are. Last week Leslie went out to talk to a prospective Seller, they have lots of work to do. Week before that Jennifer did the same, lots for the Sellers to discuss. Yesterday, I chatted with a past client about a landslide from a neighbor. See? We are happy to talk about all kinds of things.

Have a wonderful weekend!


Thursday, August 29, 2024

Those Darn Mortgage Rates ~ What Rate Is Going To Motivate You?

You won’t find anyone who’s going to argue that mortgage rates have had a big impact on housing affordability over the past couple of years. Heck yeah, they sure have! But there is some hope on the horizon. Rates have actually started to come down. You should know this already though. Recently they hit the lowest point we’ve seen in 2024, according to Freddie Mac (see graph below):

And if you’re thinking about buying a home, that may leave you wondering: how much lower are they going to go? Here’s some information that can help you know what to expect.

Expert Projections for Mortgage Rates

Experts say the overall downward trend should continue as long as inflation and the economy keeps cooling. But as new reports come out on those key indicators, there’s going to be some volatility here and there. Oh goody, more volatility.

What you need to remember is it’s not wise to let those blips distract you from the larger trend. Rates are still down roughly a full percentage point from the recent peak compared to May. That is HUGE.

And the general consensus is that rates in the low 6s are possible in the months ahead, it just depends on what happens with the economy and what the Federal Reserve decides to do moving forward. They have changed their plan several times already, but hey, who's counting?!?

Most experts are already starting to revise their 2024 mortgage rate forecasts to be more optimistic that lower rates are ahead. For example, Realtor.com says:

“Mortgage rates have been revised slightly lower as signals from the economy suggest that it will be appropriate for the Fed to begin to cut its Federal Funds rate in 2024. Our yearly mortgage rate average forecast is down to 6.7%, and we revised our year-end forecast to 6.3% from 6.5%.”

Know Your Number for Mortgage Rates

So, what does this mean for you and your plans to move? If you’ve been holding out, just waiting for rates to come down, know that it’s already happening. You're gonna have to decide, based on the expert projections and your own budget, when you’ll be willing to jump back in. As Sam Khater, Chief Economist at Freddie Mac, says:

“The decline in mortgage rates does increase prospective homebuyers’ purchasing power and should begin to pique their interest in making a move.”

As a next step, ask yourself this: what number do I want to see rates hit before I’m ready to move? Do you have a realistic number in mind?

Maybe it’s 6.25%. Maybe it’s 6.0%. Or maybe it’s once they hit 5.99%. The exact percentage where you feel comfortable kicking off your search again is personal. Once you have that number in mind, you don’t need to follow rates yourself and wait for it to become a reality.

Instead, you need to connect with a local lender. They’ll help you stay up to date on what’s happening and have a conversation about when to make your move. And once rates hit your target, they’ll be the first to let you know.

Swear, final words here:

If you’ve put your moving plans on hold because of higher than wished for interest rates rates, think about the number you want to see rates hit that would make you re-enter the market. Think about it hard, be ready to jump when they get there!

Need Lender Referrals? We've got several that we know and trust. Just ask.


Thursday, August 22, 2024

What Do Sandwiches Have to Do With Real Estate?

Are you a part of the Sandwich Generation? According to Realtor.com, that’s a name for the roughly one in six Americans who take care of their children and their parents or grandparents at the same time.

If that sounds familiar to you, juggling all the responsibilities involved certainly must have its challenges. But it turns out there’s one pretty significant benefit: it can actually make it a bit easier for you to buy a home.

How Can It Help You Buy a Home?

Realtor.com asked members of the Sandwich Generation if they agree or disagree that taking care of children and parents at the same time is helping them afford a home. A third of respondents said their situation made it easier to buy.

Here are a few ways their caretaking situation might be helping those 33% buy a home:

Sharing Expenses: If you live in a multi-generational household, you can pool your resources and split the costs. Your parents might contribute to the mortgage or help with other bills. This can make a big difference, especially in today’s housing market. It may help you afford a larger home than you could on your own.

Built-In Childcare: Having grandparents in the home could also save you money on childcare. They can help watch your kids while you’re at work, which means you can save on daycare costs too.

Beyond just the financial reasons, buying a multi-generational home has other advantages. The Profile of Home Buyers and Sellers from the National Association of Realtors (NAR) highlights some of the most popular, including:

Easier To Care for Aging Parents: It’s more convenient to take care of someone when you live with them. Also, your elderly parents may very well be happier and healthier, thanks to more social interaction and a feeling of connectedness.

Spending More Time Together: Once you live together, you get to spend more time and create even more lasting memories with your loved ones.

The Mortgage Reports sums it up this way:

“Buying a house with your parents can be a great way to ease caregiving, support young children, or simply bring loved ones closer together. And considering the steep rise in home prices over the last few years, it can make homeownership a lot more affordable.”

How a Real Estate Agent Can Help

If you’re in the Sandwich Generation and thinking about buying a multi-generational home, working with a local real estate agent is essential. Finding a home that works for so many people can be tricky. An agent will use their expertise to help you find one that meets the needs of, and has enough space for, everyone who’s going to live there.

Bottom Line

Being a part of the Sandwich Generation comes with its challenges – but it also might come with one truly great perk. If you’re looking to buy a home, your caregiving situation can actually make it a bit easier for you to afford a home. To learn more, give us a holler! We've got people sandwiching all over the place!


Friday, August 16, 2024

Sellers And Home Inspections

One of the real estate news info emails I subscribe to talked about doing work on a home prior to putting it on the market. The most important takeaway from that is ..... ASK YOUR REALTOR what is worth doing before listing.

We generally have to suggest a lot of staging. Including decluttering, moving furniture, landscape touches, cleaning, cleaning, and more cleaning.

But, a wise Seller hopefully also knows, and informs their agent, what systems in their home may need some attention. And, their agent will let them know if they should consider doing any repairs or service to those systems prior to going on market.


Some Highlights from the newsletter article:

"If you’re thinking about selling your house, it’s important to know what the home inspection is and what inspectors look for.

As supply is so obviously growing which will allow buyers  to regain some negotiation power, you may find you want to do some select repairs with a good return on investment before listing to get ahead of things a buyer may ask you to fix.

To decide what's worth tackling, you need expert advice. Reach out to a local real estate agent so you know what to prioritize."

It's definitely a touchy situation when we suggest what you should and shouldn't do. It's your call on what you do. But, depending upon the market, it can blow up an escrow if the home inspection finds a lot of items that could have been cleared up prior to listing. Hard choice to make, and, yes, it's hard for us to suggest. 

But, I truly believe the market is changing. And, the more negotiating power a buyer has, the more things a Seller is going to need to correct. Before going on market, or to keep the escrow together and get to the finish line.